A practical field guide to landing well, from opening an account to choosing a district, drawn from 300+ Blooming Nest c…
Every protection the DLD gives you, the questions to ask before signing, and the red flags a good broker will always sur…
We ran the numbers across 4,000 Dubai Harbour and Palm transactions. The view premium is bigger, and more durable, than …
Every buyer entering the Dubai market eventually reaches the same fork in the road: do you buy an off-plan unit that won't exist for two or three years, or a ready home you can move into, or rent out, next week? Both can be excellent decisions. Both can be expensive mistakes. The difference is almost never the building; it's whether the strategy matched the buyer.
Here is how we frame it for Blooming Nest clients in 2026.
Off-plan's headline advantage has always been the payment plan. Instead of financing the full price up front, you might pay 20% during construction and the remaining 80% over several years, sometimes stretching well past handover. That turns a AED 3M purchase into a sequence of manageable instalments, and it lets capital work elsewhere while the asset is built.
The real off-plan edge isn't discount, it's leverage on time. You control an appreciating asset while paying for it slowly.
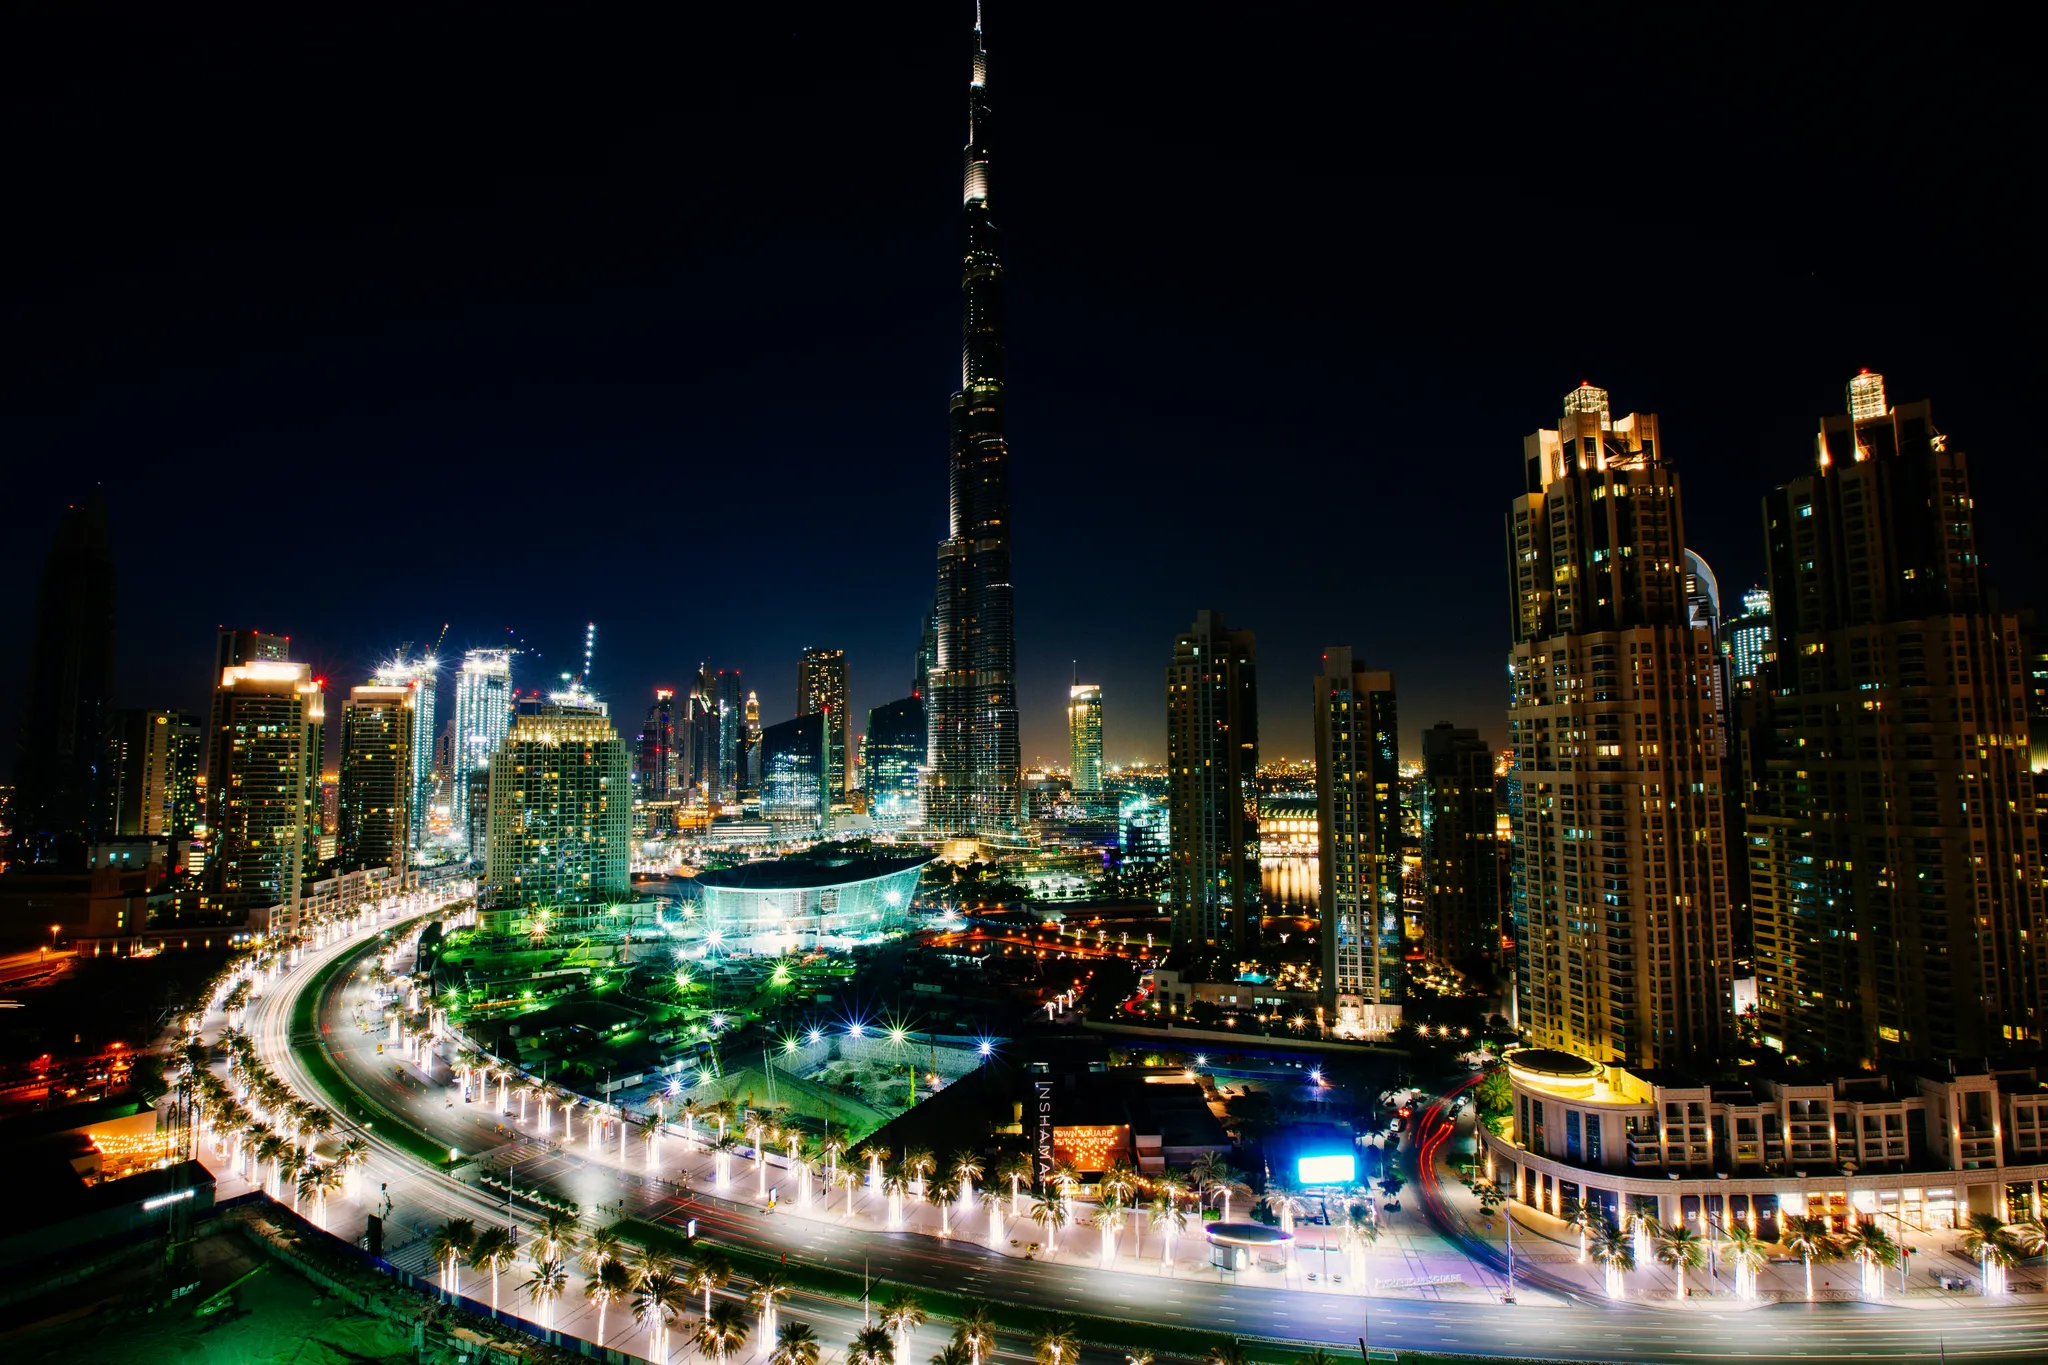
The second advantage is entry price. Launch pricing is typically the lowest a unit will ever be, and in a rising market the value at handover can meaningfully exceed what you committed to at launch. Buyers who entered Dubai Harbour and Creek Harbour at launch have, in several towers, seen double-digit appreciation before keys were even handed over.
Ready property answers off-plan's biggest weakness: it produces income from day one. In a city where prime yields still frequently sit between 6% and 8%, a completed, tenanted apartment is a cash-flowing asset the moment you own it. You can also see exactly what you're buying, the finish, the view, the actual service charge, rather than trusting a render.
For end-users relocating to the UAE, ready is often simply the practical choice: you need somewhere to live now, not in 2027. And for investors who value certainty over maximum upside, a stabilised rental beats a construction timeline.
The honest answer is that sophisticated portfolios usually hold both, off-plan for appreciation and leverage, ready for yield and stability. The mistake we see most often is buyers choosing off-plan for its low deposit without the cash flow to complete comfortably, or buying ready for "safety" while over-paying at the top of a view premium.
That is precisely the conversation a good broker exists to have. At Blooming Nest we start from your timeline, liquidity and objective, then match the strategy, and only then the building. If you'd like that analysis run against your own numbers, book a confidential consultation and we'll model both paths side by side.